Estates and Trusts
Why a Trust Can Be Essential When Planning for a Family Vacation Home
By Danielle Friedman
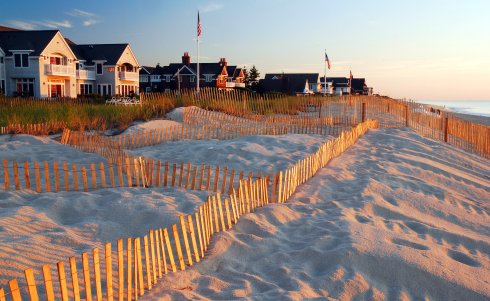
A family home often carries value far beyond its market price. It may be the place where generations gathered for holidays, summers, milestones, and ordinary moments that became family memories. But when that property is transferred without careful estate planning, even a well-intentioned decision can produce a result no one expected.
Consider the following real-life example. Jane owned a home at the Jersey Shore that had been in her family for more than 100 years. She viewed herself as the steward of the property and wanted it to remain available for future family gatherings. Her only daughter, Rachel, was close to Jane and seemed like the natural person to take over that role someday.
Jane asked her former estate planning attorney whether she should transfer the shore house to a trust for Rachel’s benefit. She was told that a trust might create additional administrative burdens and expenses. Instead, Jane signed a deed transferring the property directly to Rachel during Jane’s lifetime. At the time, the direct transfer appeared simple, inexpensive, and practical. That decision created two significant issues. First, it created a tax issue: because Rachel received the property as a lifetime gift, Rachel generally took Jane’s carryover basis in the property rather than receiving a new basis equal to the property’s fair market value. Second, it created a control issue: once the property was titled in Rachel’s individual name, Jane no longer controlled what would happen to the shore house if Rachel died, changed her estate plan, married or divorced, encountered creditor issues, or simply made different decisions about the property.
For the next few years, the family carried on as though nothing had changed, leaving Jane with the comfort of believing she had made the right decision.
Sadly, a little more than five years later, Rachel died. Rachel had lived modestly, rented an apartment, and accumulated only limited savings. Under Rachel’s Last Will and Testament, she left her estate to her close friend, Michael. Jane initially did not focus on that provision because she did not think of the shore house as part of Rachel’s estate in any meaningful way.
The following spring, Jane drove to the shore house, as she had done every year, with her car packed for the start of the summer season. When she arrived, her key no longer worked. A car she did not recognize was in the driveway. Confused, Jane knocked on the door.
Michael answered and explained that he now owned the shore house because Rachel had left all of her assets to him. Jane then realized the critical consequence of the earlier deed: by transferring the house outright to Rachel, Jane had made the property part of Rachel’s estate. Rachel’s Will controlled where the property went next.
Of course, Jane had not intended to give Michael the family shore house. Rachel likely had not intended that result either. But because the property had been titled in Rachel’s individual name, and because Rachel’s Will left her assets to Michael, Jane no longer had any legal right to the property.
The outcome was devastating. Jane had lost a home that generations of her family had cherished. She also faced the difficult task of explaining to her siblings, nieces, and nephews how a property entrusted to her care had passed outside the family. When Jane contacted us to see if we could help, unfortunately, there were few viable solutions.
This is exactly the kind of problem thoughtful trust planning can help prevent. Jane could have transferred the shore house to a trust for Rachel’s benefit, with clear instructions about who could use the property, who would manage it, how expenses would be paid, and what would happen at Rachel’s death. Depending on the structure, a properly drafted trust may also be designed to avoid unnecessary administrative complexity.
In many estate plans, a trust is a control, continuity, and protection tool. It can help keep property within the family, protect beneficiaries from unintended consequences, address creditor and divorce concerns, and provide a structure for long-term management of emotionally significant assets.
Key planning lesson: transferring property outright is not always the simplest solution when the goal is to preserve a family asset. Before signing a deed, families should consider what happens if the recipient dies, divorces, has creditor issues, changes their estate plan, or simply has different ideas about the property’s future. They should also understand the income tax consequences. A lifetime gift of appreciated real estate generally does not produce the same step-up in basis that may be available when property is inherited at death. As a result, the recipient may take the donor’s low basis and face greater capital gains tax exposure if the property is later sold.
For families with vacation homes, inherited real estate, or other legacy assets, the right plan should address legal ownership, family expectations, and tax basis. That may include a revocable trust, irrevocable trust, limited liability company, use agreement, maintenance fund, buyout mechanism, or other planning structure tailored to the family’s goals. The best solution depends on the family’s objectives, the property’s appreciation, creditor and divorce concerns, administrative tolerance, and desired tax result.