Most buyers expect environmental issues to be the real estate risk. In many deals, the larger risk is operational disruption.
Real Estate Is Involved in Most ETA Transactions
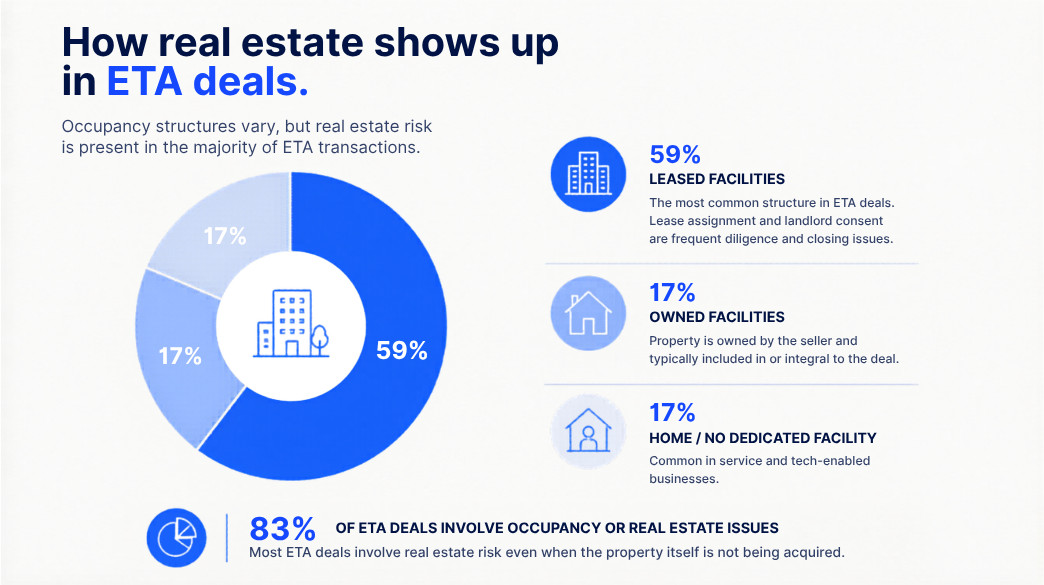
Real estate shows up in the vast majority of lower middle market transactions in some form. According to the 2025 Small Business Credit Survey published by the Federal Reserve:
- approximately 59% of operating businesses with employees operate from leased facilities
- approximately 17% operate from owned facilities
- approximately 17% primarily operate from a residence or without a dedicated operating facility
That means roughly 83% of entrepreneurship through acquisition transactions involve some form of real estate or occupancy issue.
In many deals, the primary issue is not ownership of the property itself. It is whether occupancy, control rights, lease assignment provisions, lender requirements, zoning, or permits could interfere with the business continuing to operate after closing. Those risks often become the primary real estate issues affecting the transaction.
Most Buyers Initially Focus on Environmental Risk
Environmental exposure absolutely matters. Particularly in:
- manufacturing
- industrial
- logistics
- automotive
- fuel-related operations
- older commercial corridors
Phase I and Phase II reports remain critical diligence tools. But many search funders, independent sponsors, and ETA buyers do not place enough weight on operational interruption risk.
While the business may technically exist independent of the property, operationally, it often does not.
Location Becomes Part of the Business
Most of these businesses are highly dependent on their physical operating environment.
Examples include:
- machine shops with specialized electrical infrastructure
- distributors dependent on loading access and trucking routes
- contractors relying on outdoor storage rights
- restaurants dependent on parking and liquor licensing
- healthcare operators dependent on permitted use
- manufacturers operating under grandfathered zoning protections
The issue is not simply whether the business can move. The issue is:
- cost of relocation
- operational downtime
- customer disruption
- employee retention
- permitting risk
- lender reaction
- transition timing
Many ETA buyers do not fully appreciate this until diligence deepens.
Lease Problems Often Surface After LOI
One issue that repeatedly appears in ETA deals is whether the business can continue occupying the property after closing under the existing lease arrangements.
Many buyers initially assume that the lease will (and can) transfer automatically at the time of closing. That is often incorrect.
Most commercial leases contain assignment restrictions, consent requirements, or change-of-control provisions that must be examined carefully during diligence.
Buyers need to identify:
- anti-assignment clauses
- landlord consent requirements
- change-of-control provisions
- expired lease terms
- undocumented extensions
- side agreements reflected only in emails
- use restrictions
- relocation rights held by landlords
- personal guarantees tied to the seller
While the business operated successfully under these arrangements for years, a transaction introduces scrutiny, diligence, lender review, and operational friction.
Lenders Underwrite Real Estate Issues Aggressively
Occupancy stability becomes especially important in financed transactions.
Particularly:
- SBA-backed deals
- owner-occupied industrial acquisitions
- cash flow sensitive businesses
- location-dependent operations
Lenders often focus heavily on:
- remaining lease term
- renewal rights
- assignability
- ownership structure
- related-party lease economics
- appraised value
- environmental exposure
- zoning compliance
A business with strong EBITDA but only 18 months remaining on a lease can quickly become a financing issue. Especially if the landlord has leverage during the closing process.
Owned Real Estate Creates a Separate Transaction (and Separate Issues)
Buyers often assume owned real estate simplifies the acquisition. In reality, it frequently creates a separate parallel transaction with its own diligence process, timeline, costs, and risks.
The buyer must now perform diligence on both the operating business and the real estate itself, including:
- title
- survey and boundary issues
- easements
- zoning
- environmental exposure
- permits
- deferred maintenance
- tax exposure
- utility access
- stormwater compliance
- shared access arrangements
The ownership structure also becomes critical, with many ETA deals using separate entities for the business and real estate.
For example:
- one LLC owns the operating business
- another entity owns the real estate
- the operating company leases the property from the real estate holding company
That structure often creates cleaner liability separation, financing flexibility, estate planning opportunities, and long-term control over the property.
The larger problems often appear when the business and property were never properly separated in the first place. Many older lower middle-market businesses operate under informal ownership structures where:
- the seller personally owns the property
- family members own portions of the real estate
- title ownership differs from operational control
- there is no formal lease
- occupancy economics were never documented properly
- related-party arrangements evolved informally over decades
That creates a very different set of diligence and execution risks.
Buyers now need to examine:
- who actually owns the property
- whether all owners are participating in the transaction
- whether any family members must consent
- whether the operating business has formal occupancy rights
- whether market rent materially changes EBITDA
- whether lender underwriting changes once rent is normalized
- whether personal use or mixed-use issues exist
- whether title, tax, or succession issues affect the property
- whether post-close disputes could arise around occupancy or control
Real Estate Distorts EBITDA More Than Buyers Expect
Normalized occupancy costs also frequently change the underwriting. This issue regularly shows up in entrepreneurship through acquisition transactions, causing the business to appear more profitable because the seller owns the building.
The company may operate with:
- below-market rent
- no formal lease
- favorable related-party occupancy terms
- deferred maintenance
- underreported capital needs
Once the buyer normalizes rent, maintenance, taxes, insurance, market occupancy economics, and other carrying costs, the cash flow can compress quickly. That affects:
- leverage availability
- DSCR calculations
- valuation
- purchase price expectations
- post-close cash needs
This is particularly important in manufacturing, warehouse, automotive, and hospitality acquisitions.
Zoning Problems May Remain Hidden Until Diligence
It can be a misconception to assume: “The business already operates there, so zoning must be fine.” Not always. A lack of zoning compliance can significantly disrupt operations.
Businesses sometimes operate under:
- grandfathered nonconforming uses
- historical variances
- undocumented expansions
- expired permits
- improper outdoor storage
- occupancy inconsistencies
- signage violations
- prior approvals tied to historical ownership
A transaction can trigger:
- new permit review
- lender diligence
- insurance underwriting review
- municipal scrutiny
- updated inspections
The business may have operated without issue for years, but that does not mean the use remains protected post-closing.
Real Estate Risk Can Show Up Everywhere
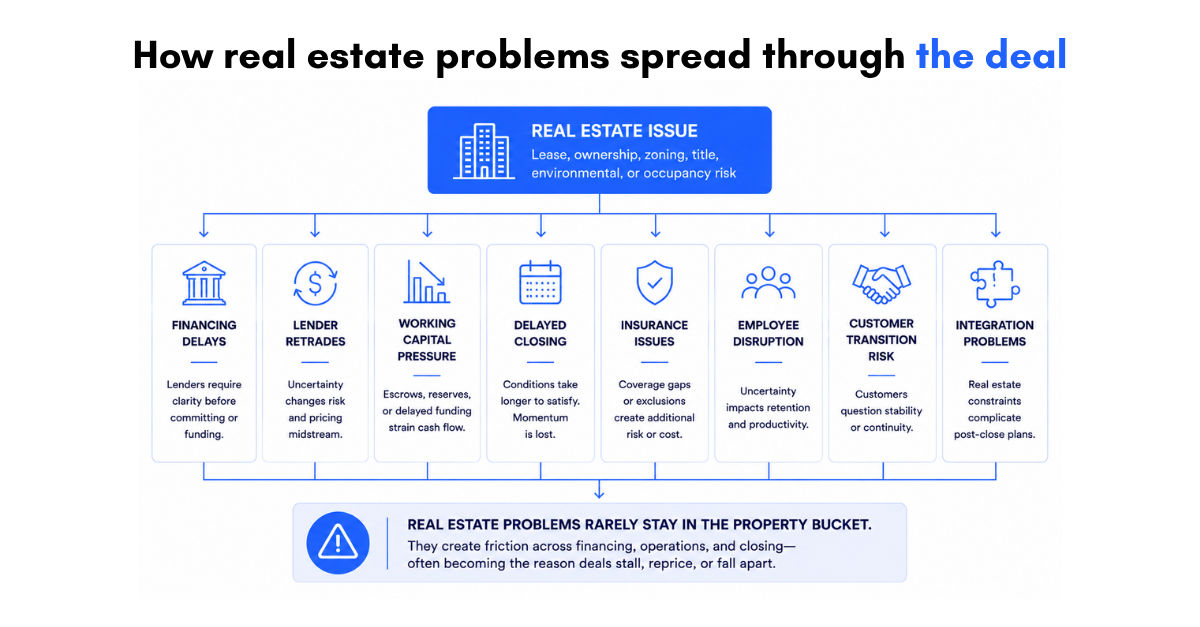
Real estate issues quickly spread into:
- financing
- operations
- integration
- employee retention
- transition planning
- insurance
- working capital
- timing of closing
The issues then become larger than the property itself.
Real estate issues are most prevalent in lower middle market acquisitions where:
- documentation evolved informally
- occupancy arrangements were relationship-driven
- operational processes were never built for institutional diligence
In these ETA deals, the answer to the real estate question ultimately controls: “Can the business continue operating the same way immediately after closing?”







